Wild Fortune Withdrawals Australia: Minimum Cashout, KYC and Processing
 Available in AU
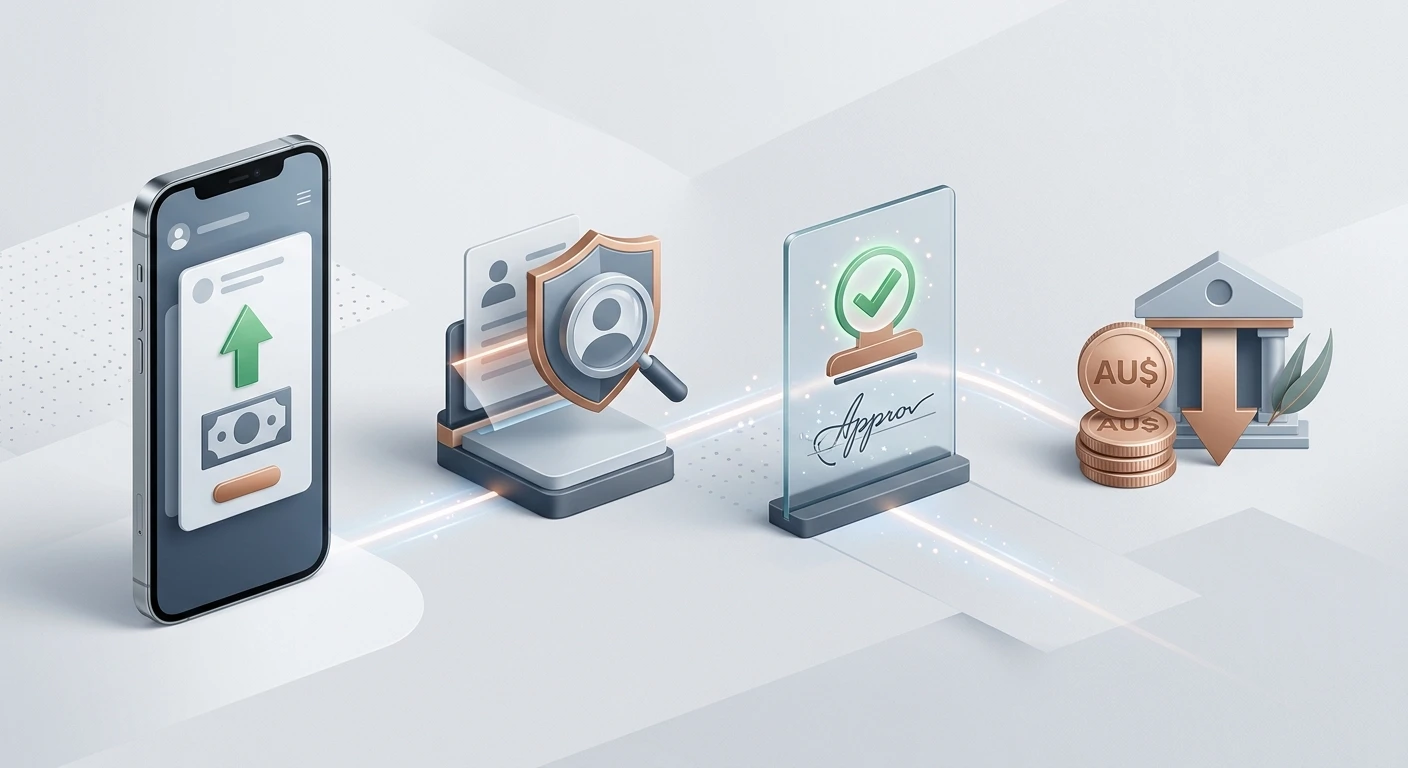
Wild Fortune’s current terms set the minimum fiat withdrawal for AUD at A$30. They also state that the maximum depends on the payment method and is shown when a withdrawal option is selected. For Australian players, that makes A$30 a verified starting point rather than a promise that every payout route has identical limits or timing.
Identity verification is a real cashout dependency. The current terms say Wild Fortune can verify an account before processing withdrawals and list a government-issued photo ID and proof of address among the minimum documents, with extra payment-method evidence possible. The operator also says it aims to process withdrawal requests within 72 hours of approval, while actual arrival depends on the chosen method and verification status.
Table of Contents
- The verified minimum withdrawal is A$30
- KYC can pause a withdrawal until verification is complete
- Understand the difference between approval and arrival
- Payment-method matching is not always one-to-one
- Deposit turnover can affect withdrawal eligibility
- What the current terms say about limits and fees
- What player reviews can and cannot tell you
- What to verify before requesting a cashout
- How to read the 72-hour processing statement
- If a withdrawal is pending
- Withdrawal priorities for Australian players
The verified minimum withdrawal is A$30
The clearest fixed figure in the current terms is the minimum fiat cashout. For AUD, Wild Fortune lists A$30. The same section does not establish one universal maximum for every payment method. Instead, it says the maximum varies by method and that the exact limit appears during withdrawal. If a requested amount is above a method limit, the operator says the payout can be split into multiple instalments.
This is why a static payment table should not replace the live cashier. The A$30 minimum is a current operator rule, but the exact ceiling for a card, bank transfer, e-wallet or another available route needs to be read from the withdrawal interface at the time of the request. The broader payment methods guide explains the difference between published payment categories and account-specific cashier options.
Wild Fortune also publishes general withdrawal-frequency limits in its terms, but those figures can change and can interact with VIP status, promotions and method-level rules. For a real cashout decision, the live account display is the practical source for the amount you can request now.
KYC can pause a withdrawal until verification is complete
Wild Fortune explicitly reserves the right to verify identity before processing a withdrawal. Its current terms list a valid government-issued photo ID, such as a passport or driver’s licence, and proof of address, such as a utility bill or bank statement, among the minimum identification documents. The operator can also request additional documentation to confirm identity or a payment method.
That means KYC is not a separate administrative topic with no connection to cashouts. If an account is selected for verification, the payout can remain pending until the required checks are completed. A player who waits until after requesting a large withdrawal to discover that documents are missing can create an avoidable delay.
The sensible preparation is basic: keep legal account details accurate, use payment methods held in your own name, and make sure current identification and address evidence are available. The full registration and KYC guide covers account verification in more detail. Verification matters here specifically because it can affect the withdrawal process.
Understand the difference between approval and arrival
The current terms say Wild Fortune aims to process withdrawal requests within 72 hours of approval. That wording matters. It describes operator processing after approval, not a guaranteed end-to-end arrival time in an Australian bank account or wallet.
There are at least four separate stages to think about. First, the player submits the request. Second, the account may be reviewed for identity, payment ownership, wagering or other account conditions. Third, Wild Fortune approves and processes the payout. Fourth, the receiving bank, card network, wallet or other provider settles the funds. A delay at the last stage is not the same thing as the casino still reviewing the request.
For cards, the terms describe Visa Original Credit Transfer and Mastercard Payment Transfer support where available, while also warning that an issuing bank can reject a card or bank transfer. They also allow Wild Fortune to use a different payout method if necessary. This is another reason not to treat a deposit route as a guaranteed withdrawal route.
Payment-method matching is not always one-to-one
Players often assume that a deposit made by one method will automatically be returned through the same method. Wild Fortune’s terms are more nuanced. They permit card withdrawals under stated conditions and say that amounts above net card deposits can be paid through an alternative method. The operator can also choose a different payout route when necessary.
Before requesting a cashout, open the current withdrawal screen and see which methods the account actually offers. If the preferred route is missing, do not force the issue by relying on an old review or an earlier saved deposit view. Contact support through the verified live-chat or email channels and ask what payout route is available for that account.
The related deposit guide explains why payment ownership and method availability should be checked before funding. Thinking about both directions before depositing can reduce friction later.
Deposit turnover can affect withdrawal eligibility
Wild Fortune’s current terms state that deposited funds must be wagered three times before they can be withdrawn. If several deposits are made without gameplay, the combined deposits are subject to that turnover rule. The operator says it can refuse a withdrawal or apply a processing fee when the requirement is not met.
This is separate from bonus wagering. A player can have no active promotional balance and still need to satisfy the deposit-turnover rule that applies to cash deposits. Before submitting a withdrawal, check the account transaction history and any remaining turnover shown by the platform rather than assuming that declining a bonus removes every wagering-related condition.
If the balance includes bonus-derived funds, read the relevant promotion terms as well. See the bonus guide for offer-specific wagering and withdrawal-cap issues.
What the current terms say about limits and fees
Wild Fortune publishes several layers of payout rules. The method-specific maximum is shown during withdrawal. The terms also describe broader daily, weekly and monthly frequency limits, and note that higher VIP levels can receive different limits at the operator’s discretion. Because these numeric limits can be commercially sensitive and can change, the live cashier and current terms should be checked together immediately before a large withdrawal.
Fees also need to be separated by source. Wild Fortune says intermediary banks can impose charges on bank transfers and that players are responsible for fees applied by their bank or payment provider. That is different from saying the casino itself charges a universal withdrawal fee, which the current terms do not support.
If cost is important, compare the payout method shown in the cashier with the receiving provider’s own fee schedule. A route with no operator-side charge can still have an external bank or wallet cost.
What player reviews can and cannot tell you
Public player feedback about Wild Fortune is mixed, including support and withdrawal complaints. This is useful as reputation context because it shows the kinds of issues some users report. It is not reliable evidence for a universal payout speed, a current method limit or a guaranteed problem.
Individual reviews rarely reveal the full account state. A complaint can involve KYC, bonus conditions, deposit turnover, bank settlement, method availability or a disputed account decision. Positive reviews have the same limitation in reverse: one fast payout does not prove that every Australian withdrawal will arrive on the same schedule.
Use reviews to identify questions worth asking, then verify operational details against the live account and current terms. For broader operator, licensing and regulatory context, see the trust and regulation.
What to verify before requesting a cashout
The most useful final check is to separate rules that are fixed in the current terms from details that can vary by account or payment route. The current terms set an A$30 minimum fiat withdrawal and allow identity verification before processing, with photo ID and proof of address among the stated minimum KYC documents. By contrast, the payout method, method-specific maximum and final settlement time can depend on what the account and receiving provider support. Read the live withdrawal screen before submitting the request, make sure any verification request has been answered, and keep bonus conditions separate from the deposit-turnover rule. This gives support a clearer starting point if a request remains pending and avoids turning an operator processing target into a guaranteed arrival time.
- Confirm that the withdrawal amount is at least the current A$30 fiat minimum.
- Open the cashier and check the exact maximum shown for the selected payout method.
- Make sure your legal name, address and account details are accurate.
- Have a valid government-issued photo ID and current proof of address available if verification is requested.
- Expect that additional payment-method evidence can be requested.
- Check whether the deposit-turnover requirement has been completed.
- Check any active bonus conditions separately from the deposit-turnover rule.
- Confirm the payout method actually offered to the account instead of assuming it matches the deposit route.
- Distinguish operator processing from settlement by the receiving bank, card network or wallet.
- If the request is large, re-read the current limit language in both the terms and the live withdrawal screen.
How to read the 72-hour processing statement
The 72-hour wording in Wild Fortune’s terms is best treated as an operator processing target after approval, not as a stopwatch that starts the moment the withdrawal button is pressed. A request can spend time in verification before approval, and the receiving payment provider can add settlement time after Wild Fortune has processed it. Those stages should be tracked separately.
If the account shows a withdrawal as pending, first look for a verification request or an unresolved account condition. If it shows approved or processed, record that status and then check the receiving bank, card or wallet. This makes support conversations more precise because you can identify whether the unresolved stage is inside the casino or with the external payment rail.
Avoid converting the operator target into claims such as “pays in three days” or “72-hour guaranteed cashout”. The current terms do not support those statements. They support a narrower and more useful conclusion: Wild Fortune aims to process approved requests within that window, with actual payout timing dependent on method and verification status.
If a withdrawal is pending
A pending status does not by itself explain the cause. Start by checking whether Wild Fortune has requested KYC documents or additional payment verification. Then check whether the deposit-turnover requirement or a bonus condition is still open. If neither appears to be the issue, review the transaction status and contact support with the request date, amount and method.
Avoid cancelling and resubmitting repeatedly unless support specifically instructs you to do so. Repeated changes can make it harder to understand which request is being reviewed. Keep transaction records or reference numbers for the withdrawal and any support conversation, but redact account identifiers if you later discuss the issue publicly.
If the operator marks a payout as processed, the next question is whether the receiving provider has completed settlement. That is when a bank or wallet reference becomes more useful than repeatedly asking the casino to reprocess an already-sent payment.
Withdrawal priorities for Australian players
The current operator terms give Australian players several concrete rules: an A$30 minimum fiat withdrawal, possible KYC before processing, photo ID and proof of address among the minimum verification documents, method-specific maximums displayed during withdrawal, and an operator target of processing requests within 72 hours of approval. None of those points guarantees an end-to-end arrival time for every payout method.
The most reliable cashout routine is to verify the account early, satisfy deposit and bonus conditions, read the live method limit, submit the request, and separate casino processing from payment-provider settlement. That gives a much clearer picture than relying on a review that labels a withdrawal “instant” or treats one user’s experience as a universal rule.
For the wider product context, see the full review.
Written by the editors at Wild Fortune Casino.